
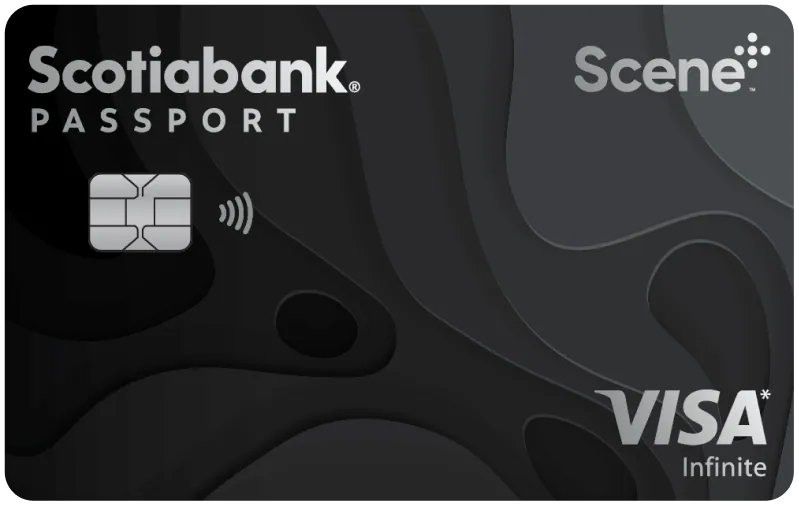
The Scotiabank Passport® Visa Infinite +* Card is a compelling premium travel card for Canadians looking for meaningful travel benefits and flexible Scene+ rewards. With no foreign transaction fees, six complimentary airport lounge visits, extensive travel insurance and strong earning opportunities in popular spending categories, the card offers a well-rounded combination of everyday rewards and travel value. The current offer of up to $1,250 in first-year welcome offers, rewards and savings adds even more potential value for eligible new cardholders.*
RateBuddyCredit card guide
Best Credit Cards with Annual Fee Rebates in Canada
- Fact checked
- Welcome offers
- First-year value
RateBuddy Card Insight
Written by
 Reviewed
A fee rebate is useful only if the account requirement works for you
Some cards offer annual fee rebates when paired with selected accounts or balances. RateBuddy helps compare the rebate condition, card fee, banking requirement, rewards, and overall usefulness.
What to compare
- Required account or balance condition
- Annual fee and rebate amount
- Rewards and welcome offer
- Overall banking relationship fit
Best Credit Cards with Annual Fee Rebates of November 2026 in Canada
Last updated
Ready to refine
Earn up to $1,350 in first year welcome offers, rewards and savings*
Get Exclusive Ratebuddy Cash Rebate:
$150
Annual fee
$150
Purchase APR
20.99%
Cash advance
22.99%
 Scotiabank®
Best for
Travel Rewards
Premium
Rewards
Best for
Travel Rewards
Premium
Rewards
Welcome-offer value
Advertised value estimate, subject to eligibility and provider requirements
$1,350
Estimated rewards from spending
Based on $1,500 in monthly spending
$0
First-year annual fee
Fee charged during the first year
$150
Estimated first-year card value
Welcome value + spending rewards − first-year fee
$1,200
View spending and reward-rate details
| Spending category | Monthly spend | Rate | Annual value |
|---|---|---|---|
| Groceries | $450 | 0% | $0 |
| Dining | $300 | 0% | $0 |
| Gas and transit | $150 | 0% | $0 |
| Travel | $75 | 0% | $0 |
| Recurring bills | $75 | 0% | $0 |
| Other purchases | $450 | 0% | $0 |
RateBuddy cash rebate
This separate rebate is not included in the card value or ranking above.
+$150
Potential first-year value with RateBuddy rebate
$1,350
Estimate notes
- No usable reward rate is configured, so spending rewards were not estimated.
This is an estimate, not a guaranteed cash return. Actual value depends on spending, eligibility, redemption choices and meeting the provider’s offer terms. Reward rates are treated as estimated cash-equivalent percentages.
Rewards program
Scene+
Card essentials
Rates, fees and requirements
The important numbers, organized so they are easy to scan and compare.
Annual fee
$150
Primary cardholder
Purchase APR
20.99%
Regular purchase rate
Cash advance APR
22.99%
Cash transaction rate
Balance transfer APR
22.99%
When available
Foreign transaction fee
0%
Foreign-currency purchases
Additional card fee
$0
Supplementary cardholder
Before you apply
Eligibility snapshot
Recommended credit score
—
Minimum personal income
$60,000
Minimum household income
$100,000
Approval, rates and credit limits are determined by the card provider.
Go for Gold: Earn up to $1100 in First-Year Value, including 65,000 bonus Scene+ points.*
Get Exclusive Ratebuddy Cash Rebate:
$150
Annual fee
$120
Purchase APR
21.99%
Cash advance
22.99%
Scotiabank®
Best for
Travel Rewards
Premium
Rewards
Best for
Travel Rewards
Premium
Rewards
Welcome-offer value
Advertised value estimate, subject to eligibility and provider requirements
$1,100
Estimated rewards from spending
Based on $1,500 in monthly spending
$0
First-year annual fee
Fee charged during the first year
$120
Estimated first-year card value
Welcome value + spending rewards − first-year fee
$980
View spending and reward-rate details
| Spending category | Monthly spend | Rate | Annual value |
|---|---|---|---|
| Groceries | $450 | 0% | $0 |
| Dining | $300 | 0% | $0 |
| Gas and transit | $150 | 0% | $0 |
| Travel | $75 | 0% | $0 |
| Recurring bills | $75 | 0% | $0 |
| Other purchases | $450 | 0% | $0 |
RateBuddy cash rebate
This separate rebate is not included in the card value or ranking above.
+$150
Potential first-year value with RateBuddy rebate
$1,130
Estimate notes
- No usable reward rate is configured, so spending rewards were not estimated.
This is an estimate, not a guaranteed cash return. Actual value depends on spending, eligibility, redemption choices and meeting the provider’s offer terms. Reward rates are treated as estimated cash-equivalent percentages.
Rewards program
Scene+
The Scotiabank Gold American Express Card is a feature-rich choice for Canadians who want strong everyday rewards alongside useful travel benefits. It earns up to 6 Scene+ points per $1 at participating grocery partners, 5 points on dining and entertainment, and 3 points on gas, transit and streaming. No foreign transaction fees, Amex Experiences and airport-lounge access add further value, while the $120 annual fee can be waived with an eligible Scotiabank bank account.
Card essentials
Rates, fees and requirements
The important numbers, organized so they are easy to scan and compare.
Annual fee
$120
Primary cardholder
Purchase APR
21.99%
Regular purchase rate
Cash advance APR
22.99%
Cash transaction rate
Balance transfer APR
—
When available
Foreign transaction fee
0%
Foreign-currency purchases
Additional card fee
$29
Supplementary cardholder
Before you apply
Eligibility snapshot
Recommended credit score
—
Minimum personal income
$12,000
Minimum household income
—
Approval, rates and credit limits are determined by the card provider.
Annual fee
$150$0
First year waived
Purchase APR
21.99%
Cash advance
23.99%
 BMO Bank of Montreal
Best for
Travel Rewards
Balance Transfer
Premium
Best for
Travel Rewards
Balance Transfer
Premium
Welcome-offer value
Advertised value estimate, subject to eligibility and provider requirements
$650
Estimated rewards from spending
Based on $1,500 in monthly spending
$306
First-year annual fee
$150 first-year fee waiver applied
$150
$0
Estimated first-year card value
Welcome value + spending rewards − first-year fee
$956
View spending and reward-rate details
| Spending category | Monthly spend | Rate | Annual value |
|---|---|---|---|
| Groceries | $450 | 1% | $54 |
| Dining | $300 | 3% | $108 |
| Gas and transit | $150 | 1% | $18 |
| Travel | $75 | 5% | $45 |
| Recurring bills | $75 | 3% | $27 |
| Other purchases | $450 | 1% | $54 |
This is an estimate, not a guaranteed cash return. Actual value depends on spending, eligibility, redemption choices and meeting the provider’s offer terms. Reward rates are treated as estimated cash-equivalent percentages.
First year free
Card essentials
Rates, fees and requirements
The important numbers, organized so they are easy to scan and compare.
Annual fee
$0 first year
Then $150 annually
Purchase APR
21.99%
Regular purchase rate
Cash advance APR
23.99%
Cash transaction rate
Balance transfer APR
—
When available
Foreign transaction fee
—
Foreign-currency purchases
Additional card fee
—
Supplementary cardholder
Before you apply
Eligibility snapshot
Recommended credit score
—
Minimum personal income
$80,000
Minimum household income
$150,000
Approval, rates and credit limits are determined by the card provider.
Annual fee
$120$0
First year waived
Purchase APR
21.99%
Cash advance
23.99%
BMO Bank of Montreal
Best for
Cash Back
Balance Transfer
Premium
Best for
Cash Back
Balance Transfer
Premium
Welcome-offer value
Advertised value estimate, subject to eligibility and provider requirements
$320
Estimated rewards from spending
Based on $1,500 in monthly spending
$441
First-year annual fee
$120 first-year fee waiver applied
$120
$0
Estimated first-year card value
Welcome value + spending rewards − first-year fee
$761
View spending and reward-rate details
| Spending category | Monthly spend | Rate | Annual value |
|---|---|---|---|
| Groceries | $450 | 5% | $270 |
| Dining | $300 | 1% | $36 |
| Gas and transit | $150 | 3% | $54 |
| Travel | $75 | 1% | $9 |
| Recurring bills | $75 | 2% | $18 |
| Other purchases | $450 | 1% | $54 |
This is an estimate, not a guaranteed cash return. Actual value depends on spending, eligibility, redemption choices and meeting the provider’s offer terms. Reward rates are treated as estimated cash-equivalent percentages.
First year free
Card essentials
Rates, fees and requirements
The important numbers, organized so they are easy to scan and compare.
Annual fee
$0 first year
Then $120 annually
Purchase APR
21.99%
Regular purchase rate
Cash advance APR
23.99%
Cash transaction rate
Balance transfer APR
—
When available
Foreign transaction fee
—
Foreign-currency purchases
Additional card fee
—
Supplementary cardholder
Before you apply
Eligibility snapshot
Recommended credit score
—
Minimum personal income
$80,000
Minimum household income
$150,000
Approval, rates and credit limits are determined by the card provider.
Annual fee
$120$0
First year waived
Purchase APR
20.99%
Cash advance
22.99%
 ATB Financial
Best for
Travel Rewards
Premium
Newcomer
Best for
Travel Rewards
Premium
Newcomer
Welcome-offer value
Advertised value estimate, subject to eligibility and provider requirements
$320
Estimated rewards from spending
Based on $1,500 in monthly spending
$369
First-year annual fee
$120 first-year fee waiver applied
$120
$0
Estimated first-year card value
Welcome value + spending rewards − first-year fee
$689
View spending and reward-rate details
| Spending category | Monthly spend | Rate | Annual value |
|---|---|---|---|
| Groceries | $450 | 3% | $162 |
| Dining | $300 | 1% | $36 |
| Gas and transit | $150 | 3% | $54 |
| Travel | $75 | 4% | $36 |
| Recurring bills | $75 | 3% | $27 |
| Other purchases | $450 | 1% | $54 |
This is an estimate, not a guaranteed cash return. Actual value depends on spending, eligibility, redemption choices and meeting the provider’s offer terms. Reward rates are treated as estimated cash-equivalent percentages.
Rewards program
ATB My Rewards
First year free
Card essentials
Rates, fees and requirements
The important numbers, organized so they are easy to scan and compare.
Annual fee
$0 first year
Then $120 annually
Purchase APR
20.99%
Regular purchase rate
Cash advance APR
22.99%
Cash transaction rate
Balance transfer APR
—
When available
Foreign transaction fee
2.90%
Foreign-currency purchases
Additional card fee
$35
Supplementary cardholder
Before you apply
Eligibility snapshot
Recommended credit score
—
Minimum personal income
$80,000
Minimum household income
$150,000
Approval, rates and credit limits are determined by the card provider.
Earn up to 80,000 bonus Scene+ points—up to $800 in value.*
Get Exclusive Ratebuddy Cash Rebate:
$200
Annual fee
$599
Purchase APR
20.99%
Cash advance
22.99%
Scotiabank®
Best for
Travel Rewards
Premium
Rewards
Best for
Travel Rewards
Premium
Rewards
Welcome-offer value
Advertised value estimate, subject to eligibility and provider requirements
$800
Estimated rewards from spending
Based on $1,500 in monthly spending
$0
First-year annual fee
Fee charged during the first year
$599
Estimated first-year card value
Welcome value + spending rewards − first-year fee
$201
View spending and reward-rate details
| Spending category | Monthly spend | Rate | Annual value |
|---|---|---|---|
| Groceries | $450 | 0% | $0 |
| Dining | $300 | 0% | $0 |
| Gas and transit | $150 | 0% | $0 |
| Travel | $75 | 0% | $0 |
| Recurring bills | $75 | 0% | $0 |
| Other purchases | $450 | 0% | $0 |
RateBuddy cash rebate
This separate rebate is not included in the card value or ranking above.
+$200
Potential first-year value with RateBuddy rebate
$401
Estimate notes
- No usable reward rate is configured, so spending rewards were not estimated.
This is an estimate, not a guaranteed cash return. Actual value depends on spending, eligibility, redemption choices and meeting the provider’s offer terms. Reward rates are treated as estimated cash-equivalent percentages.
Rewards program
Scene+
The Scotiabank Passport Visa Infinite Privilege Card offers an extensive premium travel package for frequent travellers who can make full use of its rewards and benefits. Cardholders receive a $250 annual Scene+ Travel credit, 10 complimentary lounge visits per cardholder, no foreign transaction fees and access to premium airport, hotel, dining and lifestyle experiences. Strong Scene+ earning and comprehensive travel insurance further support its premium positioning.
Card essentials
Rates, fees and requirements
The important numbers, organized so they are easy to scan and compare.
Annual fee
$599
Primary cardholder
Purchase APR
20.99%
Regular purchase rate
Cash advance APR
22.99%
Cash transaction rate
Balance transfer APR
—
When available
Foreign transaction fee
0%
Foreign-currency purchases
Additional card fee
$199
Supplementary cardholder
Before you apply
Eligibility snapshot
Recommended credit score
—
Minimum personal income
$150,000
Minimum household income
$200,000
Approval, rates and credit limits are determined by the card provider.
Annual fee
$29$0
First year waived
Purchase APR
13.99%
Cash advance
15.99%
BMO Bank of Montreal
Best for
Low Interest
Balance Transfer
Best for
Low Interest
Balance Transfer
Welcome-offer value
Advertised value estimate, subject to eligibility and provider requirements
$29
Estimated rewards from spending
Based on $1,500 in monthly spending
$0
First-year annual fee
$29 first-year fee waiver applied
$29
$0
Estimated first-year card value
Welcome value + spending rewards − first-year fee
$29
View spending and reward-rate details
| Spending category | Monthly spend | Rate | Annual value |
|---|---|---|---|
| Groceries | $450 | 0% | $0 |
| Dining | $300 | 0% | $0 |
| Gas and transit | $150 | 0% | $0 |
| Travel | $75 | 0% | $0 |
| Recurring bills | $75 | 0% | $0 |
| Other purchases | $450 | 0% | $0 |
Estimate notes
- No usable reward rate is configured, so spending rewards were not estimated.
This is an estimate, not a guaranteed cash return. Actual value depends on spending, eligibility, redemption choices and meeting the provider’s offer terms. Reward rates are treated as estimated cash-equivalent percentages.
First year free
Card essentials
Rates, fees and requirements
The important numbers, organized so they are easy to scan and compare.
Annual fee
$0 first year
Then $29 annually
Purchase APR
13.99%
Regular purchase rate
Cash advance APR
15.99%
Cash transaction rate
Balance transfer APR
—
When available
Foreign transaction fee
—
Foreign-currency purchases
Additional card fee
—
Supplementary cardholder
Before you apply
Eligibility snapshot
Recommended credit score
—
Minimum personal income
—
Minimum household income
—
Approval, rates and credit limits are determined by the card provider.
Annual fee
$19
Purchase APR
19.99%
Cash advance
22.99%
Card essentials
Rates, fees and requirements
The important numbers, organized so they are easy to scan and compare.
Annual fee
$19
Primary cardholder
Purchase APR
19.99%
Regular purchase rate
Cash advance APR
22.99%
Cash transaction rate
Balance transfer APR
—
When available
Foreign transaction fee
2.90%
Foreign-currency purchases
Additional card fee
$0
Supplementary cardholder
Before you apply
Eligibility snapshot
Recommended credit score
—
Minimum personal income
—
Minimum household income
—
Approval, rates and credit limits are determined by the card provider.
RateBuddy
Math. Not Marketing.
We calculate the true value to save you every penny.
Data-Driven Logic
Rankings based on hard numbers (fees vs rewards), not advertising budgets.
100% Unbiased
We highlight the "gotchas" and fees just as clearly as the perks.
Direct & Secure
No data harvesting. We send you straight to the bank's secure official site.
Why Choose a Credit Card?
Beyond simple convenience, the right credit card offers a layer of consumer protection, financial leverage, and rewards that debit cards or cash simply cannot match.
Zero Liability Protection
Canadian credit cards come with robust federal protections against unauthorized transactions. Unlike cash, which is gone forever if lost, or debit cards which are directly linked to your bank funds, a credit card offers a buffer. If your card is used fraudulently, you are generally not held liable for those charges once reported. This keeps your actual bank account safe and liquid while the bank investigates the issue. It provides peace of mind in an era of increasing digital fraud.
Value-Added Rewards
Every purchase you make is an opportunity to earn a return on your spending. Whether you prefer travel points, merchandise, or cash back, using a credit card allows you to get value back on expenses you were going to pay anyway. Over the course of a year, a standard 1-2% reward rate can accumulate into hundreds of dollars in free groceries or flights. It is effectively a discount on your entire lifestyle, provided you pay your balance in full. Why pay full price with cash when you can earn a rebate with credit?
Building Credit History
Your credit score is your financial passport in Canada, dictating your ability to rent apartments, get a mortgage, or finance a car. Responsible credit card use is one of the most effective and fastest ways to establish this history. By using a card and paying it off on time every month, you demonstrate reliability to future lenders. A long, positive history with a credit card accounts for a significant portion of your credit score calculation. Without this history, obtaining major loans later in life can be difficult or much more expensive.
RATEBUDDY TOOLKIT
Crunch The Numbers
See exactly how much you can save, earn, or pay off.
Explore the Ecosystem
Discover more ways to save, earn, and optimize your wallet.
Not sure what you need?
Explore other possibilities.
Credit Cards is great, but sometimes a different card fits your lifestyle better. Use our Smart Finder to see what else you qualify for.
Cash Back
Earn money on daily spend.
Travel Rewards
Best for frequent flyers.
SPEC SHEET
Find best cards by features:
Filter our database by the specific perks and coverages that matter to you.
ISSUERS
Browse by Bank & Issuer:
Filter our database to see offers from specific Canadian financial institutions.
LOYALTY PROGRAMS
Browse by Reward Program:
Already collect points? Find the card that accelerates your existing balance.
A little clarity, before you choose
Make the card fit your life.
Explore the bigger picture, check the numbers and find the tradeoffs that matter to you.
The Canadian picture
The Bank of Canada’s 2025 survey estimates that 89% of adults owned a credit card. Credit cards accounted for 48.2% of purchases recorded in its diary by number; 31% of cardholders reported not paying their full balance in the previous month.
Source: Bank of Canada · 2025 Methods-of-Payment Survey (published August 2026)What this means for your comparisonOur interpretation: a card can be an everyday payment tool or an expensive way to borrow. The right comparison starts with how you repay, then considers rewards and benefits.
When is an annual fee worth paying?Measure usable benefits against a practical alternative, including renewal costs.
An annual fee buys a package. Its value depends on which parts of that package you can use and what a sensible alternative would cost. A card with a fee can be worthwhile; a card without one can still be the stronger choice for your situation.
Use incremental value, not the brochure total
Compare the fee card with a practical no-fee or lower-fee alternative. Subtract the rewards you would already earn on that alternative before valuing the upgrade. Then add benefits you would genuinely use, at an amount you would reasonably pay for them. FCAC’s card-selection guidance highlights comparing annual fees with usable benefits and checking similar no-fee options.
Retail prices can exaggerate personal value. If a lounge pass is marketed at $60 but you would otherwise eat at the gate for $15, $60 is not necessarily your saving. If a travel credit requires a more expensive booking channel, compare the complete booking price. Benefits you already receive from another card or an employer should not be counted twice.
Worked example: the renewal-year upgrade test
| Incremental annual value or cost | Amount |
|---|---|
| Extra rewards compared with the alternative | +$150 |
| Two usable benefits valued at $25 each | +$50 |
| Additional annual fee | −$120 |
| Net advantage | +$80 |
If the benefits go unused, the advantage falls to $30. If the extra rewards also fall from $150 to $100, the card is $20 behind. That sensitivity matters more than adding up every listed benefit at its advertised price.
For rewards alone, a $120 additional fee with an extra 0.5 percentage points of return requires $24,000 of eligible annual spending to break even: $120 ÷ 0.005. Caps, exclusions, interest and other costs are not included in that simplified threshold.
Insurance needs a coverage comparison
Emergency medical, trip cancellation, trip interruption, rental-car damage and purchase protection are different benefits. The Government of Canada advises checking policy conditions, exclusions and requirements before travel. Its guidance also distinguishes medical coverage from interruption and cancellation, and highlights issues such as pre-existing conditions and trip duration.
Read the current certificate for the people, trip and purchases you want covered. Check age, eligible family members, the length of the trip, payment requirements, exclusions, deductible and the claims process. Assign value only after confirming that it meets a need you would otherwise pay to cover. Do not assign an insurance policy’s maximum payout as an annual benefit value.
A fee waiver can have another cost
A linked bank account or first-year waiver can change the comparison, but check its conditions. For illustration, keeping an additional $5,000 idle to obtain a card-fee waiver has a $150 annual opportunity cost if that money could otherwise earn 3% before tax. If the bank account also replaces services you would buy anyway, include those benefits separately. The result depends on your actual alternatives, not a universal interest assumption.
For foreign-currency spending, compare the entire conversion cost and rewards rather than just one fee label. A card billed in U.S. dollars also needs a plan for how you acquire and repay those dollars. Keep currency assumptions consistent before comparing a Canadian-dollar annual fee with savings on foreign purchases.
Evaluate the year you will renew
Remove one-time welcome points and promotional fee waivers, add any supplementary-card cost and use normal spending. Put a reminder before renewal to check whether your travel or household needs have changed. For business cards, include administration and employee-account needs, while keeping any tax treatment outside this general consumer comparison.
A fair fee comparison: count additional value you can use, deduct the additional cost and repeat the check without first-year incentives.
Do you need more than one credit card?Understand when a second card adds useful value and when it adds work.
A second card is useful when it has a clear job. It might improve a spending category, provide a backup where your main card is not accepted or separate business purchases. Owning more cards does not, by itself, mean you have a better setup.
Look for complementary roles
Start with what your current card does poorly. If it already earns useful rewards on most purchases, a second card needs to fill a meaningful gap. Two cards with similar fees, rewards and benefits may add very little. A backup may be helpful, but judge its value alongside the cost and work of another account.
Merchant acceptance should be checked where you shop. Holding different networks can offer alternatives, but no particular combination guarantees acceptance everywhere. For travel, keep the backup usable and accessible; two cards that are both unavailable during an account issue do not provide the resilience you expected.
Worked example: measure the extra value only
Suppose $6,000 of annual spending currently earns 1%. Moving exactly that spending to a second hypothetical card earning 3% adds $120 in gross rewards. With a $60 annual fee, the extra value is $60 a year, assuming all purchases qualify and both cards are paid in full.
$6,000 × (3% − 1%) − $60 = $60 of additional annual value.
Counting all $180 earned on the second card as a gain would ignore the $60 you already earned on the first. Consider whether the remaining $60 is worth managing another statement and payment date.
More available credit does not remove the debt
FCAC notes that credit applications can create hard inquiries, and closing an older account can reduce available credit and affect credit history. Those effects depend on the overall file. Avoid interpreting a new limit as a guaranteed improvement in your score.
As arithmetic, a $1,000 balance against $4,000 of total limits is 25% utilization. Adding an unused $2,000 limit changes that ratio to about 16.7%, while the debt remains $1,000. Closing that added account returns the ratio to 25%. This example explains the ratio, not a predicted score movement or a reason to apply for unnecessary credit.
Design a routine you can actually maintain
Assign each card a simple role and review the combined total, not just each account in isolation. Two balances of $750 are still $1,500 of spending. Keep enough funds available for payments, check statements for errors and set reminders that leave room for processing time. Automation is useful only when the funding account can support it.
Reward caps, renewal dates, supplementary-card fees and subscription payments are easy to overlook across several accounts. Keep a small record of each card’s main purpose and annual cost. Review whether it earned enough incremental value over the last year, rather than renewing because it once had a strong welcome offer.
Adding and closing accounts both need thought
A card you rarely use may still have fees, recurring charges or rewards that need attention. Before closing one, check those items and the issuer’s process for settling the balance. A product switch may be an option, but ask how it affects fees, benefits and rewards instead of assuming the old terms carry over.
Do not build a strategy around repeatedly collecting welcome bonuses without reading eligibility restrictions. Aeroplan’s program terms, for example, address misuse of new-card bonuses across products and institutions. A welcome offer is subject to its rules; it is not a reliable substitute for recurring value.
A manageable setup: every card has a purpose, its extra value is measurable and the combined payments fit your budget.
PAYMENT NETWORKS
Browse by Network:
Filter by Visa, Mastercard, or Amex acceptance.
CARD LEVELS
Browse Cards by Tier:
From entry-level options to exclusive black cards. Find the eligibility level that fits you.
KNOWLEDGE BASE
Frequently Asked Questions
Common questions about Compare Cards with Rebates Cards and financial strategy.
Disclaimer: Information is for educational purposes only and does not constitute financial or legal advice. Terms subject to change by issuers.
Most Canadian credit cards charge a fee (typically 2.5%) on top of the exchange rate for any transaction made in a currency other than Canadian dollars. Cards marketed as 'No Foreign Transaction Fee' generally waive this 2.5% surcharge, though the exchange rate itself is still determined by the card network (Visa/Mastercard/Amex).
It can be, depending on your usage. Premium cards with annual fees often come with higher reward earn rates, comprehensive insurance, and perks like lounge access. If the value of the rewards and benefits you utilize exceeds the cost of the fee, the card may offer a positive net value.
You should contact your card issuer immediately to lock or cancel the card. Many issuers also offer a 'Lock Card' feature in their mobile app which can prevent new transactions instantly. Once reported, the issuer will typically send a replacement card with a new number.
A cash advance occurs when you withdraw cash from an ATM using your credit card or transfer funds from the card to a bank account. These transactions typically incur a fee (e.g., $5) and interest starts accruing immediately (no grace period), often at a higher rate than purchases.
It might. Cancelling an older card reduces your 'Average Age of Accounts,' which is a factor in your credit score. It also reduces your total available credit, which could increase your utilization ratio. If the card has no annual fee, it is often better to keep it open and use it occasionally to keep the history active.
Still have questions?
Visit our Financial Education Hub
FINANCIAL WELLNESS
Tools & Resources
Master your money with our suite of free calculators and guides.